Financial Data Analysis Projects
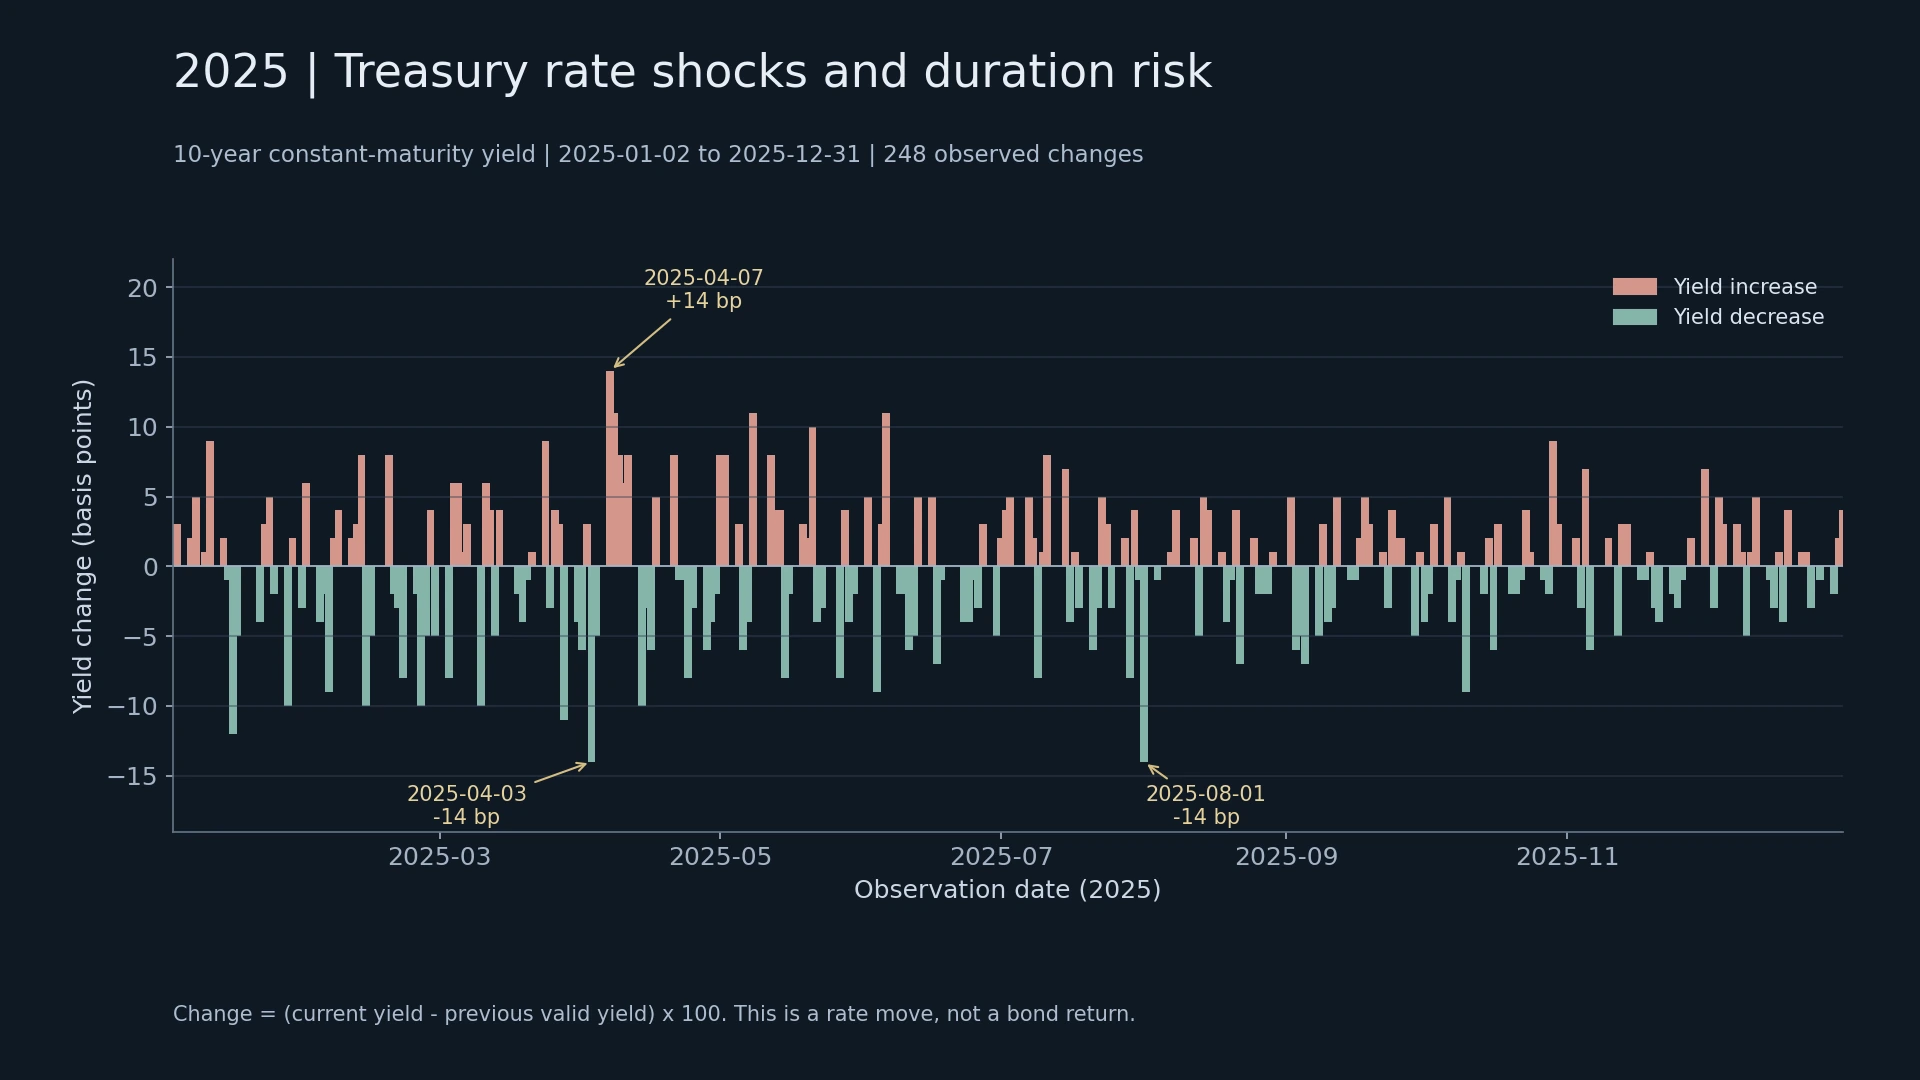
2025 Bond Duration and Yield Risk: From Observed Shocks to DV01
Use Treasury bond 91282CLW9 to reconcile auction pricing, calculate duration and DV01, and test repricing approximation errors under yield shocks.

2025 Treasury Term Spread: Changes and Analytical Limits
Decompose short- and long-end contributions to the yield spread, examine curve steepening and distinguish portfolio risk from bank net interest margin.
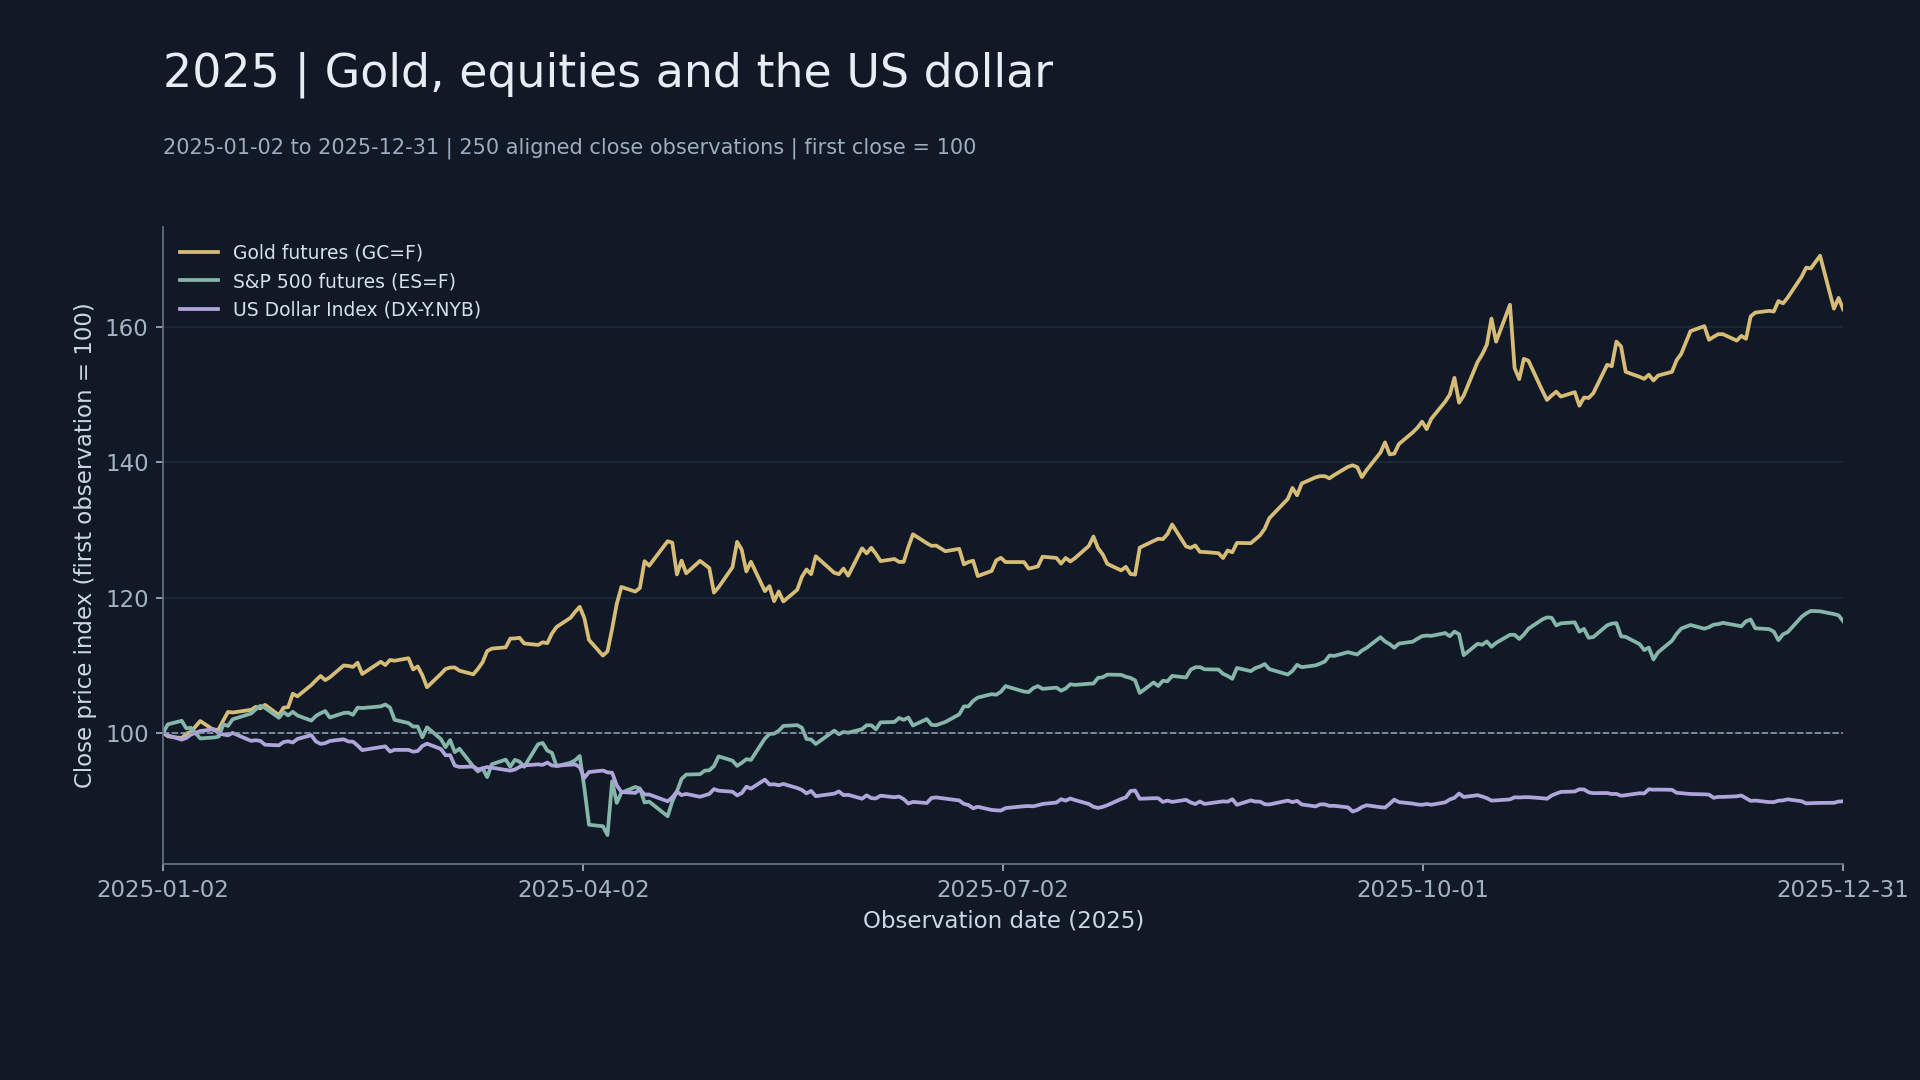
2025 Multi-Asset Allocation Research: Returns, Correlations and Diversification
Compare full-sample and short-window correlations, examine cross-asset behavior during equity stress and define the limits of allocation conclusions.
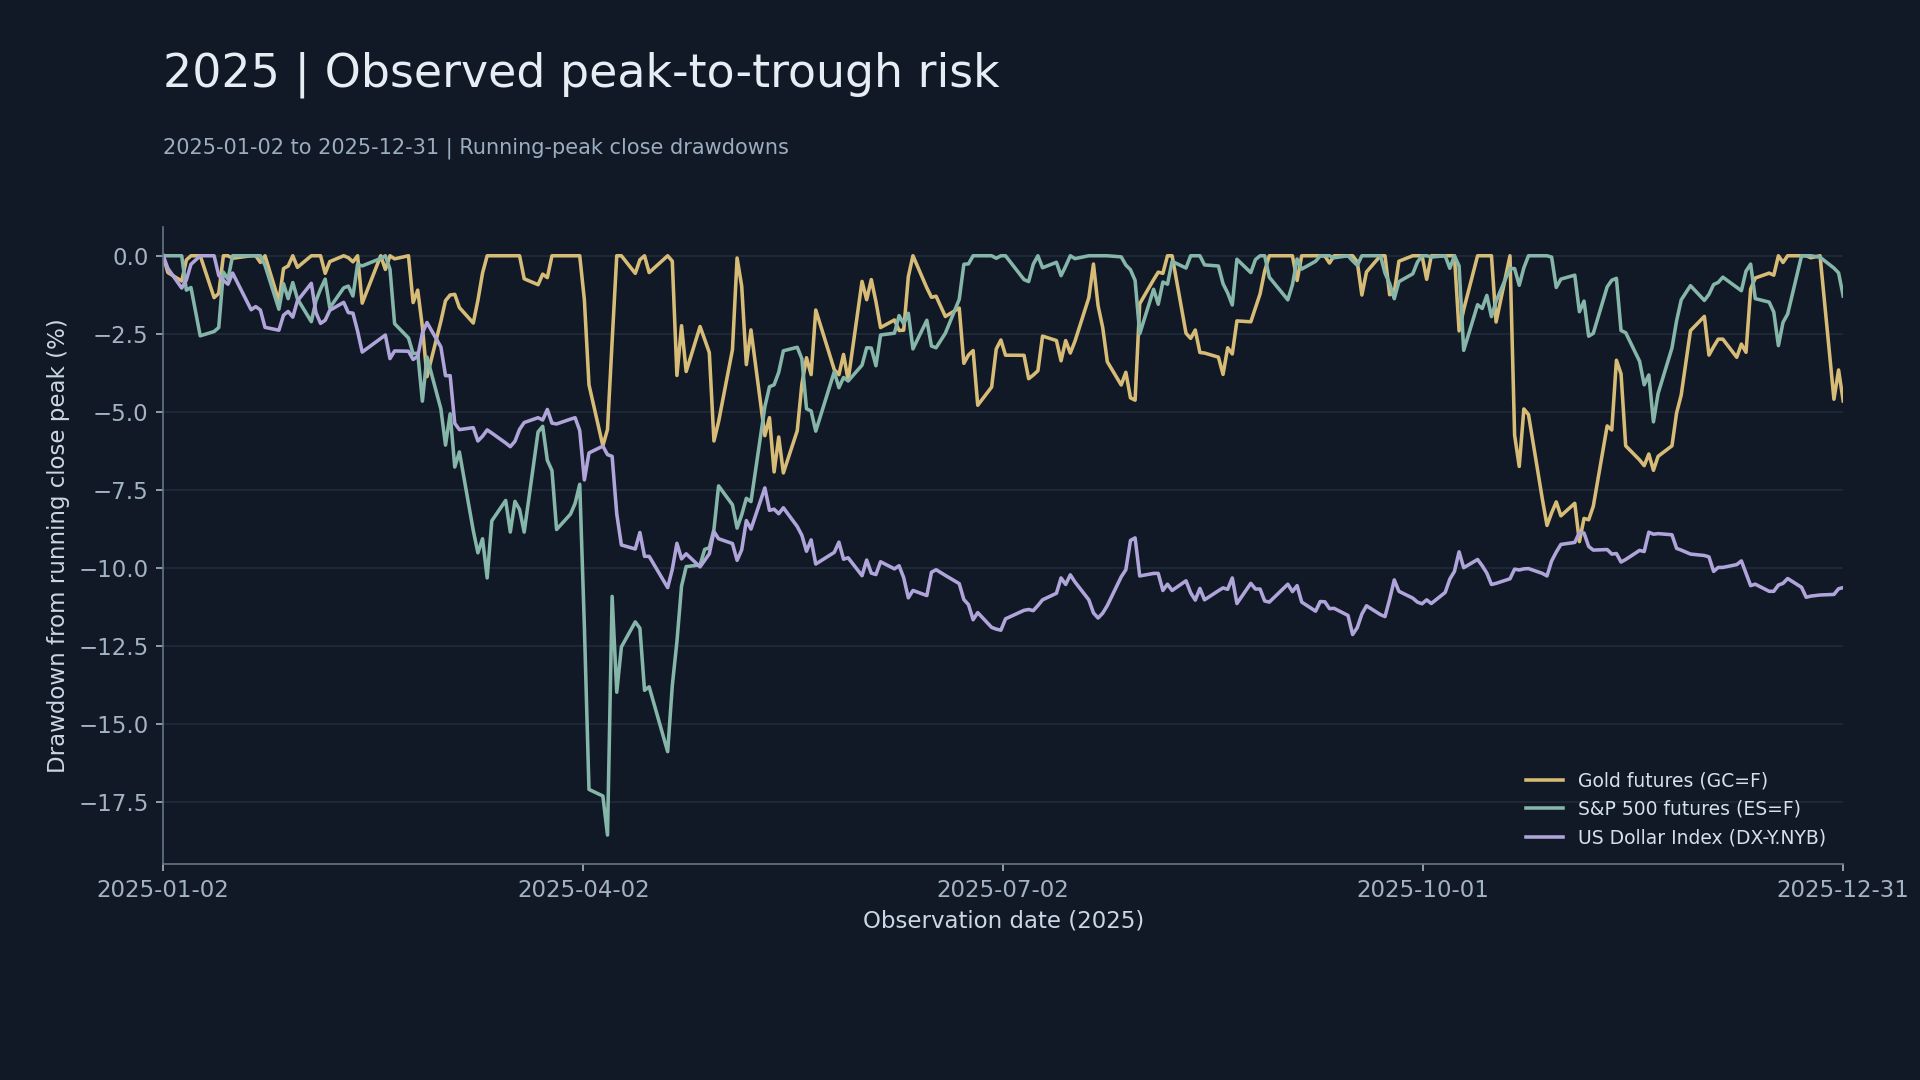
2025 Observed Drawdowns and Dollar Risk Scenarios
Identify observed peaks, troughs and recovery dates; examine recovery requirements and distinguish notional exposure, account equity and scenario P&L.

2025 U.S. Treasury Yields: Short-End and Long-End Changes
Compare short- and long-end yields by quarter, distinguishing yield direction, curve shifts and their effects on cash-flow valuation.